
Key Takeaways:
- Most lenders allow you to borrow up to 80–90% of your home’s value minus what you owe on your mortgage.
- Your credit score, debt-to-income ratio, and home equity all directly influence your HELOC borrowing limit.
- HELOCs work like a revolving credit line, giving you flexibility to borrow, repay, and borrow again during the draw period.
If you own a home in Florida and you’ve been building equity over the years, a Home Equity Line of Credit — commonly called a HELOC — can be one of the most powerful financial tools available to you. But before you start mentally earmarking funds for a kitchen renovation or debt consolidation, the first question you need answered is straightforward: how much can you actually borrow?
The answer depends on several moving pieces. Let’s break them down clearly so you know exactly where you stand before you ever speak to a lender.
What Is a HELOC and How Does It Work?
A HELOC is a revolving line of credit secured by your home. Unlike a personal loan or a home equity loan — which gives you a lump sum upfront — a HELOC works more like a credit card. You get access to a credit limit, you draw from it as needed, repay it, and draw from it again during what’s called the draw period (typically 10 years).
After the draw period ends, you enter the repayment period, usually lasting 10 to 20 years, during which you can no longer pull funds and must begin repaying the principal plus interest.
Because your home serves as collateral, HELOCs often come with lower interest rates than unsecured debt. That’s a significant advantage — but it’s also why lenders scrutinize your financials closely before approving you.
The Core Formula: How Lenders Calculate Your HELOC Limit
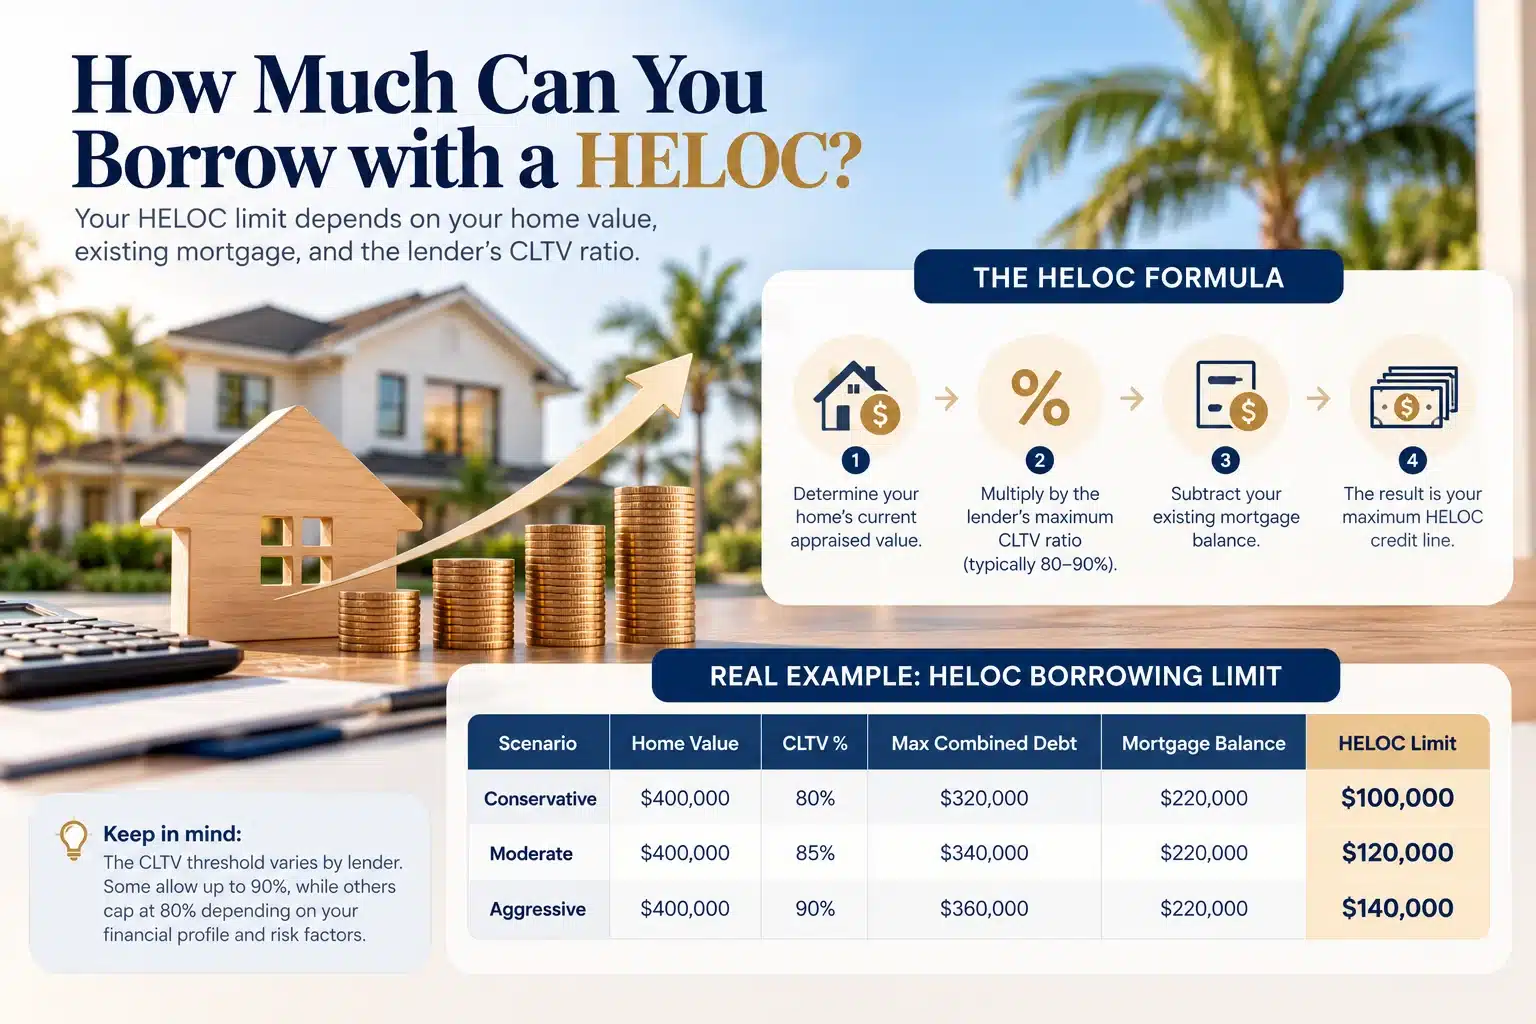
Your HELOC borrowing limit isn’t arbitrary. Lenders use a specific calculation to determine the maximum amount you can access. Here’s how it works:
Step 1: Determine your home’s current appraised value.
Step 2: Multiply that value by the lender’s maximum combined loan-to-value (CLTV) ratio — typically 80% to 90%.
Step 3: Subtract your existing mortgage balance.
The result is your maximum HELOC credit line.
Here’s a practical example:
| Scenario | Home Value | CLTV % | Max Combined Debt | Mortgage Balance | HELOC Limit |
|---|---|---|---|---|---|
| Conservative | $400,000 | 80% | $320,000 | $220,000 | $100,000 |
| Moderate | $400,000 | 85% | $340,000 | $220,000 | $120,000 |
| Aggressive | $400,000 | 90% | $360,000 | $220,000 | $140,000 |
The CLTV threshold varies by lender. Some will go up to 90%, while others cap at 80% depending on their risk tolerance and your financial profile. Understanding this calculation puts you in control of the conversation before you walk into any lender’s office.
Key Factors That Affect How Much You Can Borrow
Your home value and mortgage balance set the ceiling. But several personal financial factors determine whether you actually reach that ceiling or fall somewhere below it.
Home Equity
Equity is the foundation of a HELOC. You need to have enough of it for a lender to feel comfortable extending credit. Most lenders require that you retain at least 10–20% equity in your home after the HELOC is established. If you bought your home recently with a small down payment and haven’t paid down much principal, your usable equity might be limited regardless of how much your home has appreciated.
Florida homeowners who purchased property several years ago — especially in high-demand markets like Tampa, Orlando, or South Florida — may be sitting on substantially more equity than they realize. Getting a current appraisal is worth the investment before assuming where you stand.
Credit Score
Your credit score directly impacts both your approval odds and the interest rate you’ll receive. For most lenders:
- 700 or above — Strong approval odds with competitive rates
- 660–699 — Likely approval, but potentially higher rates
- Below 640 — Many lenders will decline, though some options may exist
A higher credit score signals lower risk to the lender, which can also mean a higher approved credit limit. If your score needs work, it may be worth taking three to six months to pay down revolving balances and address any negative marks before applying.
Debt-to-Income Ratio (DTI)
Lenders want to see that your monthly debt obligations — including the new HELOC payment — won’t consume too much of your gross monthly income. Most lenders prefer a DTI of 43% or lower, though some will go up to 50% for well-qualified borrowers.
To calculate yours: add up all your monthly debt payments (mortgage, car loans, student loans, minimum credit card payments, and the estimated HELOC payment), then divide by your gross monthly income.
Employment and Income Verification
Stable, verifiable income matters. Self-employed borrowers, independent contractors, and those with variable commission income may face additional documentation requirements. Lenders want confidence that you can service the debt, especially since HELOC payments can fluctuate with interest rates (most HELOCs carry variable rates tied to the prime rate).
HELOC vs. Other Home Equity Products: What Makes Sense for Your Goal?
A HELOC isn’t the right product for every situation. Before committing, it helps to understand how it compares to other financing options — including some you might not have considered.
“A HELOC gives you financial flexibility that most loan products simply can’t match. You only pay interest on what you actually use, which makes it an efficient borrowing tool when managed responsibly.”
If you’re looking at a one-time large expense — like a full home addition — a home equity loan with a fixed rate and fixed payment might give you more predictability. If you’re eyeing a purchase rather than a renovation, exploring FHA loan programs could open doors for buyers who don’t have substantial home equity to tap yet.
For veterans and active-duty service members, VA home loans offer exceptional benefits that may outperform a HELOC depending on your situation. And for borrowers with strong credit profiles seeking a purchase or refinance, conventional loan options might present a more strategic path depending on your financial goals.
The point isn’t to steer you away from a HELOC — it’s that understanding your full menu of options leads to smarter decisions.
What Can You Use a HELOC For?
Once you know how much you can borrow, the next natural question is what lenders expect you to do with it. The short answer: almost anything.
Common uses include:
- Home improvements and renovations — This is the most common use, and it can even increase your home’s value, compounding your equity position.
- Debt consolidation — Rolling high-interest credit card balances into a lower-rate HELOC can reduce monthly payments significantly.
- Education expenses — College tuition and related costs are a frequent use case for families with built-up home equity.
- Emergency fund access — Some homeowners open a HELOC and keep it at a zero balance simply to have a safety net available.
- Business investment — Entrepreneurs sometimes leverage home equity to fund business expenses, though this carries added risk.
There’s no law mandating how you use the funds (beyond general lending regulations), but it’s worth being strategic. Using your home as collateral for consumer purchases like vacations or non-essential spending introduces risk that isn’t worth taking lightly.
The Variable Rate Reality: What It Means for Your Payments
Most HELOCs carry variable interest rates, typically indexed to the Wall Street Journal prime rate plus a margin set by your lender. When rates rise — as they did sharply in recent years — so do your monthly payments.
This isn’t a dealbreaker, but it’s a critical piece of financial awareness. If you draw heavily on your HELOC and rates climb, your payment obligations can increase meaningfully. Some lenders offer the ability to convert a portion of your HELOC balance to a fixed rate, which can provide stability if you’re carrying a large balance.
When evaluating your HELOC limit, factor in your comfort level with payment variability — not just the maximum amount you’re eligible to borrow.
How to Maximize Your HELOC Borrowing Power
If your initial calculation suggests a lower limit than you’d hoped for, there are legitimate ways to improve your position before applying.
Pay down your mortgage. Even modest additional principal payments increase your equity and expand your available credit ceiling.
Improve your credit score. Pay down revolving credit balances, avoid opening new accounts, and correct any errors on your credit report in the months before applying.
Reduce your DTI. Paying off a car loan or personal loan before applying can meaningfully shift your debt-to-income ratio in your favor.
Get a home appraisal. Market conditions in Florida have pushed property values higher in many areas. An updated appraisal reflecting current market value may reveal more equity than you expected based on your original purchase price.
Shop multiple lenders. CLTV limits, rate margins, fees, and credit requirements vary from one lender to another. What one lender declines, another may approve — and the terms can differ substantially.
Working with an experienced mortgage broker like the team at Liberty Mortgage Lending Group means you’re not limited to a single institution’s guidelines. Access to a broader network of lenders means more options, more competitive rates, and a process that’s tailored to your specific situation.
If you’re exploring other government loan programs alongside your HELOC research, a broker can help you compare those side by side in terms of cost, structure, and long-term impact on your financial picture.
Timing Matters: When Is the Right Time to Apply?
The best time to apply for a HELOC is when your equity is strong, your credit score is healthy, and your income is stable. That combination typically produces the most favorable terms and the highest credit limits.
Applying during a period of financial stress — reduced income, elevated debt, or recent credit inquiries — tends to result in lower limits, higher rates, or outright denial. If you’re not quite there yet, a short-term plan to improve your position before applying can pay off considerably.
Interest rate environment matters too. Since most HELOCs carry variable rates, applying when rates are elevated means your initial payments will be higher. Some borrowers choose to wait for rate stability, while others open a HELOC at a zero balance to lock in their approved limit, then draw from it strategically over time.
Frequently Asked Questions
How much equity do I need to qualify for a HELOC?
Most lenders require at least 15–20% equity remaining in your home after the HELOC is established. That means if your home is worth $350,000, you’d typically need your combined debt (mortgage plus HELOC) to stay below $280,000–$297,500.
Can I get a HELOC if I have a second mortgage?
Yes, but it complicates the calculation. Any existing second mortgage counts toward your combined loan-to-value ratio, reducing how much you can borrow through a new HELOC. Some lenders won’t approve a third lien position at all.
How long does it take to get a HELOC approved?
Approval timelines vary, but most HELOCs close within two to six weeks. The appraisal process and title work are typically the longest steps. Working with an experienced mortgage team can help keep the process moving efficiently.
Does a HELOC affect my credit score?
Opening a HELOC will result in a hard inquiry on your credit report, which may temporarily lower your score by a few points. Over time, responsible use — drawing and repaying the balance — can actually support a positive credit history.
What happens if my home value drops after I open a HELOC?
Lenders can reduce or freeze your HELOC credit line if your home’s value declines significantly or if your financial situation changes materially. This is one reason why over-relying on a HELOC limit as a permanent financial resource carries risk.
Conclusion
Understanding how much you can borrow with a HELOC comes down to knowing your home’s equity position, your financial profile, and the specific terms different lenders are willing to offer. The formula itself is straightforward — but the variables that influence the outcome are worth understanding deeply before you apply.
Florida homeowners are in a strong position in many markets right now, with property values that have supported substantial equity accumulation over the past several years. That equity can be a powerful resource when accessed thoughtfully.
Whether you’re ready to apply or still gathering information, Liberty Mortgage Lending Group is here to help you understand your options, run accurate numbers, and connect with lenders who fit your situation. Our team works with borrowers across Florida to make home financing decisions clearer and more manageable — from first conversation through closing.
Ready to find out exactly how much you could access through a HELOC? Contact the team at Liberty Mortgage Lending Group today for a no-pressure conversation about your home equity options. Whether a HELOC is the right move or another loan program fits your goals better, we’ll give you the honest guidance you need to move forward with confidence.