
Key Takeaways:
- A HELOC lets you borrow against your home’s equity with a revolving credit line, making it one of the most flexible financing tools for renovation projects.
- Interest rates on HELOCs are typically variable, meaning your monthly payments can shift — understanding the draw and repayment periods is essential before you commit.
- Florida homeowners working with a local mortgage team can access personalized guidance to determine whether a HELOC or another loan product better fits their renovation goals.
If your kitchen is stuck in 2003, your bathroom needs a complete gut job, or you’ve been putting off a roof replacement for longer than you’d like to admit, you’re probably thinking about how to pay for it. Home renovations are expensive. Even modest projects can run well into five figures, and major remodels can easily exceed $100,000. That’s where a Home Equity Line of Credit — commonly called a HELOC — comes in.
A HELOC lets you borrow against the equity you’ve already built in your home. Think of it as a credit card secured by your property. You get access to a revolving credit line, draw from it as needed, and only pay interest on what you actually use. For renovations specifically, this structure makes a lot of sense.
What Exactly Is a HELOC?
A HELOC is a second mortgage product that gives you access to a credit line based on the difference between your home’s current market value and what you still owe on your mortgage. If your home is worth $400,000 and you owe $220,000, you have $180,000 in equity. Most lenders will let you borrow up to 80% to 85% of your home’s value — minus your existing mortgage balance.
Using that example: 85% of $400,000 is $340,000. Subtract the $220,000 mortgage balance, and you could potentially access up to $120,000 through a HELOC.
There are two distinct phases to a HELOC:
The Draw Period: Typically 5 to 10 years. During this time, you can withdraw funds up to your credit limit, make payments, and borrow again — much like a credit card. Most lenders only require interest payments during the draw period, though paying down principal is always smart.
The Repayment Period: Usually 10 to 20 years. Once the draw period ends, you can no longer access the line. You begin repaying both principal and interest, and monthly payments can increase significantly.
Understanding this timeline is critical. Plenty of homeowners get comfortable with low interest-only payments during the draw period, then face sticker shock when full repayment kicks in.
Why a HELOC Works Well for Renovations
Home renovation projects rarely come with a fixed, predictable invoice. Contractors uncover problems. Timelines extend. Material costs change. A HELOC’s revolving structure adapts to that reality in ways a traditional lump-sum loan can’t.
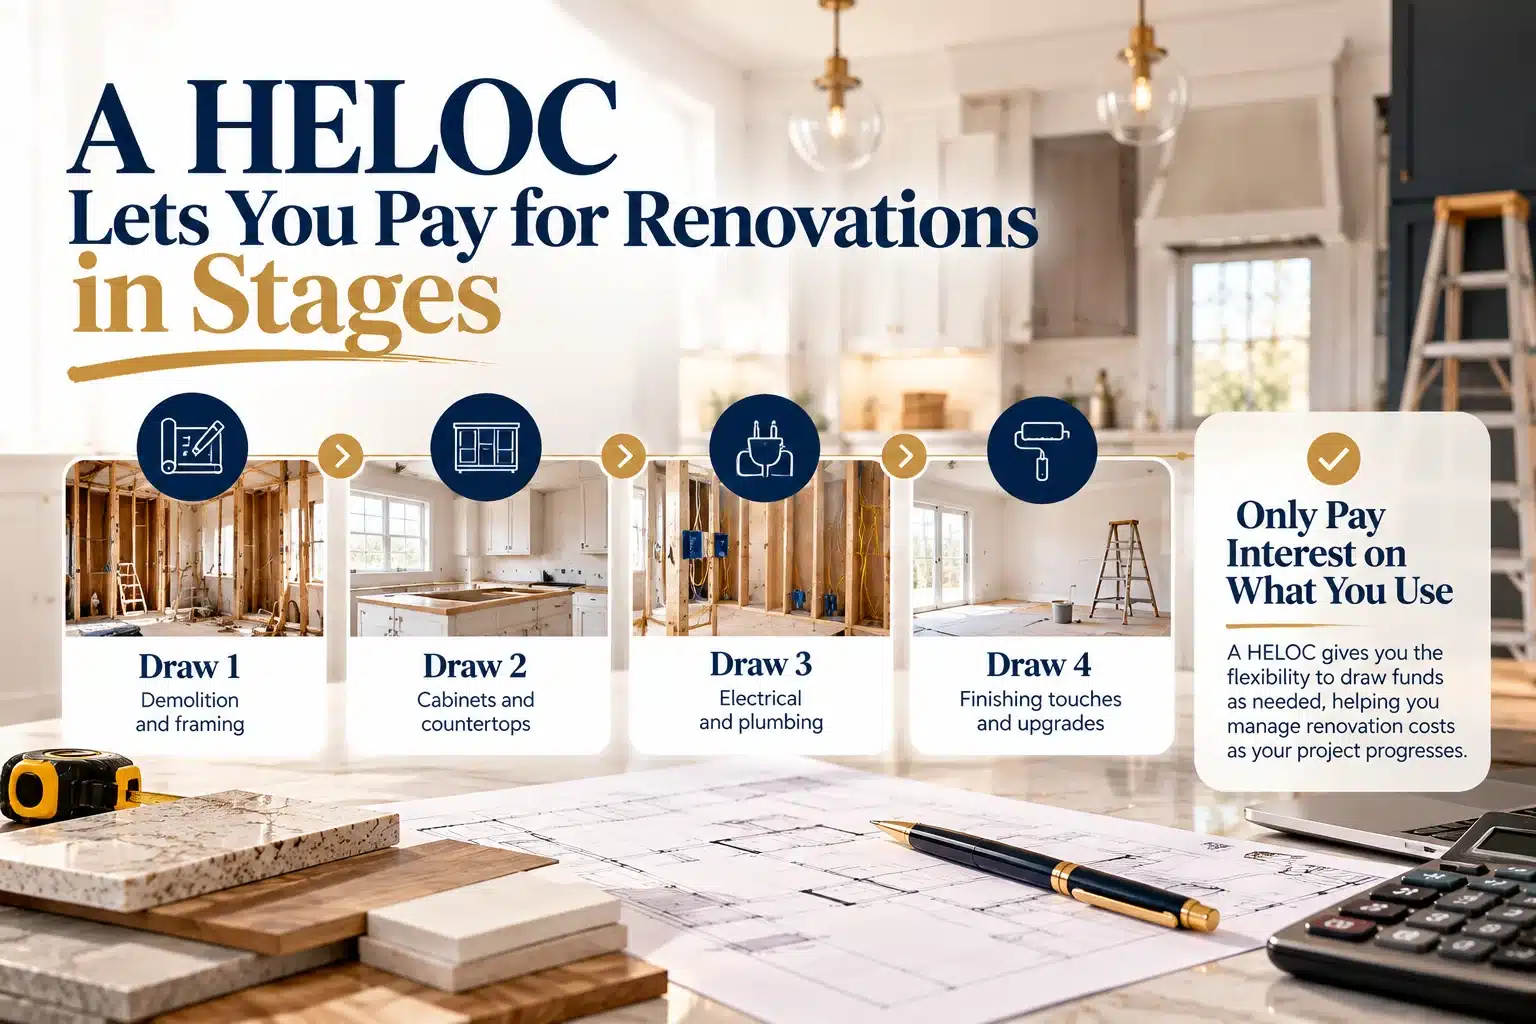
You don’t pull the full $80,000 the moment you get approved. You draw $15,000 for demolition and framing. Another $22,000 when cabinets and countertops are ordered. More when the electrical work gets done. You only pay interest on what you’ve actually drawn at any given moment — which keeps costs manageable during the construction phase.
Compare that to a personal loan or a home improvement loan, where you’d be paying interest on the full balance from day one regardless of where the project stands.
For Florida homeowners specifically, this matters. Renovation costs here can be highly variable depending on whether you’re dealing with hurricane-hardening improvements, impact windows, roof replacements, or pool additions — all common projects in the state. A flexible credit line aligns with how renovation spending actually unfolds.
HELOC vs. Other Home Renovation Financing Options
You have choices when it comes to financing a renovation. Here’s how a HELOC stacks up against the most common alternatives.
| Financing Option | Loan Structure | Interest Rate Type | Best For |
|---|---|---|---|
| HELOC | Revolving credit line | Variable | Phased, multi-stage renovations |
| Home Equity Loan | Lump sum | Fixed | Single large project with known cost |
| Cash-Out Refinance | New first mortgage | Fixed or Variable | Accessing large equity + rate reset |
| Personal Loan | Lump sum | Typically fixed | Smaller projects, no equity required |
| FHA 203(k) Loan | Purchase + renovation | Fixed or adjustable | Buying a fixer-upper home |
A cash-out refinance might make more sense if current rates are favorable and you want to roll everything into one monthly payment. A home equity loan is better when you know exactly what the project costs and want payment predictability. But for most homeowners doing phased renovations, a HELOC is the most efficient tool available.
It’s worth noting that if you’re a first-time buyer considering a fixer-upper, an FHA loan with renovation provisions might be worth exploring before you even get to the HELOC conversation.
HELOC Interest Rates: What You’re Actually Dealing With
HELOCs carry variable interest rates tied to an index — most commonly the prime rate. When the Fed raises rates, your HELOC rate typically moves up. When rates fall, your rate usually drops. That variability is the main risk borrowers underestimate.
Some lenders offer a fixed-rate conversion option, allowing you to lock in a rate on a portion of your outstanding balance. This hybrid approach can reduce exposure to rate swings while preserving some flexibility.
In a high-rate environment, scrutinize the rate closely. A HELOC at prime + 0.5% looks different at 8.5% than it did at 3.75%. Run the math on your projected draws and make sure the interest costs align with the value the renovation adds to your property.
“The key question isn’t just whether you can access equity — it’s whether the cost of accessing that equity makes financial sense relative to the return on your renovation investment.”
Factors that influence the rate you’re offered include your credit score, your combined loan-to-value ratio (CLTV), your income, and your debt-to-income ratio. Borrowers with credit scores above 740 and strong income documentation typically secure the most competitive terms.
How to Qualify for a HELOC in Florida
Lenders evaluate several key criteria when you apply for a HELOC. Here’s what you need to have in order before you apply:
- Sufficient equity: Most lenders require at least 15% to 20% equity remaining in your home after the HELOC is issued.
- Credit score: A minimum of 620 is often required, but 700+ puts you in a much better position for rate and approval purposes.
- Debt-to-income ratio (DTI): Generally, lenders prefer a DTI at or below 43%. Some will go higher with compensating factors.
- Verified income: W-2s, tax returns, or bank statements depending on how your income is structured.
- Home appraisal: Lenders will order an appraisal — or in some cases a desktop appraisal — to confirm your home’s current market value.
- Property type: Primary residences are easiest to qualify with. Investment properties and second homes face more scrutiny.
The application process is similar to getting a first mortgage. You’ll submit documentation, go through underwriting, and close on the credit line before funds become accessible.
What Renovations Actually Make Sense With a HELOC?
Not all renovation spending is equal from a financial standpoint. Some projects add significant resale value. Others are purely quality-of-life improvements. Both are valid reasons to renovate — just go in with clear eyes about what you’re optimizing for.
High-ROI projects worth financing with a HELOC:
- Kitchen remodels (minor to mid-range) — typically return 60%–80% of cost at resale
- Bathroom additions or remodels — strong resale impact, especially in competitive markets
- Roof replacement — essential maintenance that protects property value
- Impact windows and hurricane-rated doors — particularly valuable in Florida for insurance premiums and resale
- HVAC system replacement — a baseline expectation for buyers in Florida’s climate
- Adding livable square footage — additions and garage conversions can significantly increase appraised value
Projects that may be harder to recoup:
- Luxury pools in non-pool markets (though in Florida, pools are often expected)
- High-end finishes in a neighborhood with a low price ceiling
- Purely cosmetic updates in homes that need structural attention first
The point isn’t to avoid personal preference renovations — it’s to make an informed decision about how much debt you’re taking on relative to the value being created.
HELOC Tax Considerations
The Tax Cuts and Jobs Act of 2017 changed the rules around HELOC interest deductibility. Under current law, you can only deduct HELOC interest if the funds are used to “buy, build, or substantially improve” your home. If you use a HELOC to fund a kitchen renovation or add a room, the interest is generally deductible — subject to the overall mortgage interest deduction limits.
If you use HELOC funds for something unrelated to the home — paying off credit cards, funding a vacation, covering tuition — that interest is not deductible.
Always work with a CPA or tax advisor to confirm deductibility based on your specific situation. Tax law has nuances, and your filing status and overall mortgage balance affect what you can actually claim.
How Liberty Mortgage Lending Group Helps Florida Homeowners
If you’re a Florida homeowner considering a HELOC for renovations, working with a knowledgeable local mortgage team gives you a meaningful advantage. The mortgage landscape in Florida has unique dynamics — property values, insurance costs, and market conditions vary significantly across the state, from Tampa Bay to Miami to the Panhandle.
At Liberty Mortgage Lending Group, we help Florida homeowners understand all available options, not just the most obvious one. Sometimes a HELOC is exactly the right tool. Other times, a conventional loan refinance with cash-out makes more sense. In specific circumstances — particularly for veterans — a VA home loan refinance can offer significant advantages over a second lien.
We work through the numbers with you. That means running scenarios based on your current equity position, your credit profile, the scope of your renovation, and your long-term financial goals. Our team brings the personal attention of a local mortgage broker with access to a wide range of competitive loan options across Florida.
For homeowners exploring more specialized financing — physicians with non-traditional income documentation, for example — we also offer guidance on doctor loan programs that can be structured to accommodate renovation goals alongside home purchases.
If you’re not sure whether a HELOC, a cash-out refinance, or another product fits your situation best, that’s exactly the kind of conversation we’re built for.
Common HELOC Mistakes to Avoid
Getting a HELOC approved is only half the equation. How you manage the line once it’s open is what determines whether it helps or hurts you financially.
- Treating it like free money. Your home secures the line. If you can’t repay it, you can lose your house. Borrow with a clear plan.
- Ignoring the repayment period. Low interest-only payments during the draw period can create a false sense of affordability. Model out what full principal + interest payments look like before you commit.
- Maxing out the line immediately. Just because you have access to $100,000 doesn’t mean you should use $100,000. Draw conservatively in line with actual project milestones.
- Not locking in rates on large balances. If your lender offers a rate-lock option and you’re carrying a large balance heading into a rising rate environment, use it.
- Skipping the appraisal prep. Your approved credit limit depends on your appraised value. Before applying, take stock of your home’s condition and address any obvious issues that could drag down the appraisal.
Conclusion
A HELOC is one of the most practical and cost-efficient ways to fund home renovations — particularly for projects that unfold in stages or carry some budget uncertainty. The revolving structure, the flexibility to draw and repay on your timeline, and the typically lower rates compared to personal loans or credit cards make it a compelling option for homeowners who’ve built meaningful equity.
That said, it’s not without risk. Variable rates, a two-phase repayment structure, and the fact that your home serves as collateral all demand that you go in educated and prepared. Running the numbers carefully — and working with a mortgage team that knows your local market — makes the difference between a HELOC that accelerates your goals and one that creates financial stress.
Florida homeowners ready to explore their options can connect with Liberty Mortgage Lending Group for personalized guidance on HELOCs and the full range of financing solutions available to you. Whether your project is a kitchen overhaul, a full-home renovation, or a critical repair you can’t put off any longer, understanding your equity options is the smartest first step.
Frequently Asked Questions About HELOCs for Home Renovations
What credit score do I need to qualify for a HELOC?
Most lenders require a minimum credit score of 620, but you’ll access significantly better rates and terms with a score of 700 or higher. Borrowers above 740 typically qualify for the most competitive HELOC offers available.
How long does it take to get a HELOC approved?
The timeline varies by lender, but most HELOC applications take between 2 and 6 weeks from application to closing. This includes processing your documentation, ordering an appraisal, and completing underwriting.
Can I use a HELOC to pay for a full home renovation?
Yes. A HELOC can be used to fund partial or complete home renovations. The credit limit is determined by your available equity, your credit profile, and your lender’s loan-to-value requirements. For large projects, confirm your available equity supports the full scope of work before starting.
Is HELOC interest tax-deductible for renovations?
Generally, yes — if the funds are used to substantially improve the home securing the loan. Under current IRS rules, interest on a HELOC used for qualified home improvements is deductible subject to overall mortgage interest limitations. Consult a tax professional for guidance specific to your situation.
What happens if I sell my home while I have a HELOC open?
When you sell your home, the HELOC balance is paid off at closing from the sale proceeds, just like your primary mortgage. You’ll need to factor the outstanding HELOC balance into your net proceeds calculation when evaluating whether the time is right to sell.